




You may recognize the hospital name on an old bill but have no idea why MedConn Collection Agency LLC is now involved. MedConn has been used as a third-party collector for hospital patient accounts, while the hospital or healthcare provider remains the source of the underlying medical account.
Before paying, identify the exact hospital account MedConn is trying to collect and compare the amount being requested with the provider’s records. Payments, credits, adjustments, and the balance sent for collection can all affect whether the amount now being requested matches the patient’s account history.
The first question is not simply how often MedConn has called. It is whether the right account and the right balance are being collected.
Why Is MedConn Collection Agency Contacting Me About a Hospital Bill?
MedConn Collection Agency LLC may be contacting you because a hospital or healthcare provider placed a patient account with the agency for collection.
That does not make MedConn the hospital. The supplied information supports treating MedConn as a third-party collector handling hospital patient accounts, but it does not establish that MedConn purchased or owns every account it handles.
Start by identifying the healthcare provider named in the collection communication and matching it to your billing records. The provider’s records can show how the balance developed, while MedConn’s notices show what amount it was asked to collect.
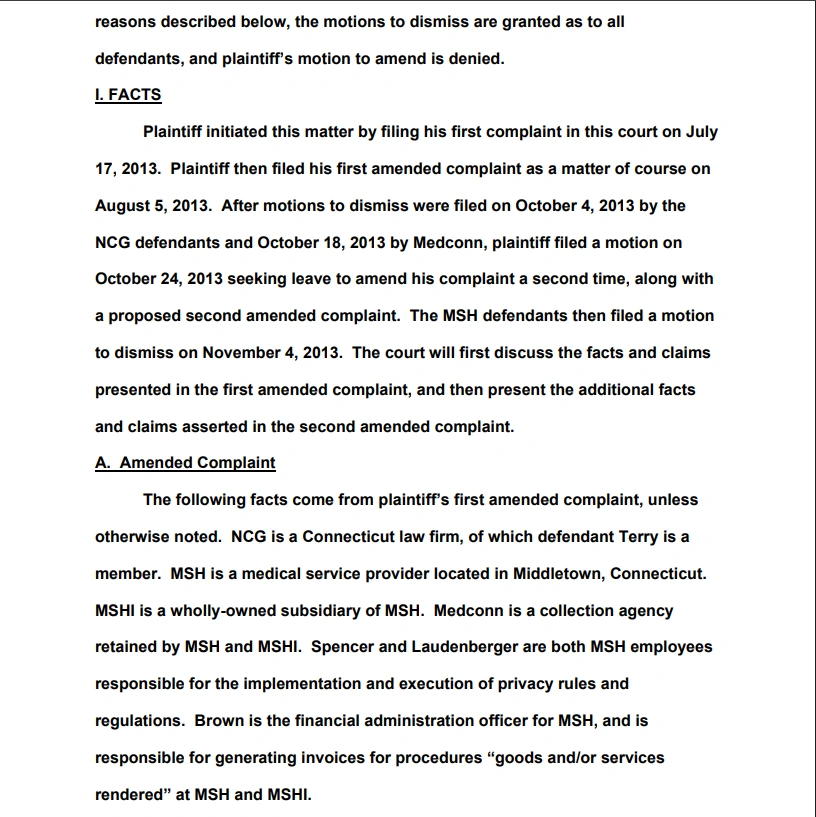
Source Name: Devine v. Terry et al., Memorandum of Decision, Document 64
One of the first things we compare in a medical collection file is the provider’s account history against the amount presented by the collection agency.
Which Hospital Account Has Been Placed With MedConn?
You should identify the exact patient account connected to MedConn’s collection request before deciding whether the amount is correct.
Recognizing the hospital name alone may not be enough. A consumer may have had more than one visit, procedure, or patient balance with the same provider. Review the account number, provider name, dates shown on your statements, and the amount MedConn identifies.
Useful records include:
| Record | Why It Matters |
| Hospital statements | Help identify the patient account and earlier balance. |
| Patient account history or ledger | Shows charges, payments, credits, adjustments, and the running balance. |
| MedConn collection notice | Shows the account and amount MedConn is attempting to collect. |
| Payment records | Can establish whether money was paid before or after the account was placed for collection. |
Do not assume that every medical bill from the same provider became part of the MedConn account.
Does the Balance MedConn Is Collecting Match the Hospital’s Records?
The amount MedConn is requesting should be compared with the hospital’s account history before you decide whether to pay.
A collection notice shows the amount being requested, but it does not necessarily show the complete history of how the hospital arrived at that balance. Start with the provider’s records and look for payments, credits, later adjustments, and the balance near the time collection began.
Then compare that history with MedConn’s notice.
| What To Check | Why It Matters |
| Provider and patient account | Confirms that the collection request belongs to the correct medical account. |
| Hospital balance history | Shows how the amount developed before collection. |
| Payments and receipts | Helps identify money that may need to be reflected in the balance. |
| Credits and adjustments | May explain why an earlier statement differs from the collection amount. |
| MedConn notice | Shows what account and amount the collector is requesting. |
What matters first in these files is whether the provider’s final account balance and the collector’s opening balance tell the same story. A difference does not automatically establish wrongdoing, but it identifies something to investigate before payment.
What Should I Do If the Hospital and MedConn Show Different Balances?
If the hospital records and MedConn’s collection amount do not match, identify where the difference occurred before treating either figure as the final amount owed.
The problem may involve the underlying patient account, information supplied for collection, or a later payment or adjustment. Keep the two dispute pathways separate because the hospital and MedConn perform different roles.
Disputing the Underlying Hospital Account
A dispute with the healthcare provider concerns the patient account itself. Review the hospital’s ledger, statements, receipts, credits, and adjustments to determine how the provider calculated the balance.
If a payment or adjustment appears in your records but not in the hospital’s account history, that discrepancy needs to be addressed at the provider level.
Disputing the Amount MedConn Is Collecting
A dispute involving MedConn Collection Agency LLC concerns what the agency is requesting and the account information it is relying on.
Compare MedConn’s notice with the provider records. Preserve any written dispute and any response you receive.
We often look at both record sets together because resolving a provider-side accounting problem and evaluating a collector’s demand are related, but they are not the same process.
What Should I Document If MedConn Keeps Calling About the Account?
Save evidence of the calls and connect each communication to the hospital account MedConn is attempting to collect.
Keep call logs, screenshots, voicemails, letters, and written communications with MedConn Collection Agency LLC. Note the date, time, phone number, and what was discussed when you can do so accurately.
Also keep the hospital billing records connected to those calls. A phone log can show the communication history, but it does not establish whether the underlying account or amount is accurate.
If MedConn is acting as a third-party debt collector on a qualifying consumer debt, federal debt-collection rules may apply to its conduct. That analysis should remain focused on MedConn’s actions rather than automatically attributing the same rules to the hospital.
When Should I Consider Legal Help With a MedConn Medical Collection?
Legal review may be useful when you cannot reconcile the hospital’s records with the amount MedConn Collection Agency LLC is collecting, when a documented payment or adjustment appears missing, or when collection communications themselves raise concerns.
Consumer Rights Law Firm PLLC may compare the patient account history, MedConn notices, payment evidence, and call records to determine which actor’s records require closer investigation. Keeping those records together can help distinguish an underlying balance problem from a collection-communication issue.
| Item | Details |
| Phone | +1 (877) 700-5790 |
| help@consumerlawfirmcenter.com | |
| Website | consumerlawfirmcenter.com |
| Address | 133 Main Street, Second Floor, North Andover, MA 01845 |
| Fax | 844-636-9909 |
| Better Business Bureau | CRLF Better Business Bureau Profile |
Success Stories
Absolutely amazing experience with Matt, he holds a very optimistic attitude, a wealth of knowledge around his profession, and the best part is how exceptional his communication is while going through the process. He always kept me up to date and provided feedback live time. Overall an awesome resource, and I would recommend him to any family, friend, or colleague!
I was being harassed by a debtor collector that wouldn’t provide me any information whatsoever. I contacted the firm the guaranteed my issue would be resolved and I wouldn’t have to pay anything out pocket! They when the case and the debt is gone and I did spend a dime! Thank you so much!
Absolutely thrilled with Consumer Rights Law Firm. Matthew put a stop to the harassment instantly, and handled my case promptly, efficiently and much to my satisfaction. Matthew was extremely friendly, compassionate and communicative and made me feel at ease with the entire process, knowing I could trust him to handle everything for me. Resolution was very quick and more than satisfactory. Appreciate Matthew and CRLF for protecting me and providing peace of mind.
Frequently Asked Questions
What if I paid the hospital shoartly before my account was sent to MedConn?
Keep the receipt or payment confirmation and compare the payment date with the hospital’s account history and MedConn’s collection amount. A payment made near the placement date may be especially important when reconstructing the balance.
Can I still contact the hospital after my account has been placed with MedConn?
The hospital may still have records needed to explain the underlying patient account, including charges, payments, credits, and adjustments. Those records can remain important even when collection activity is being handled by MedConn.
What should I check if a MedConn-related account appears on my credit report?
First identify exactly what appears on the report and which entity is listed as furnishing the information. Compare the reported balance and account details with your provider and collection records because a credit-report dispute is separate from disputing the underlying medical balance.
