




Are you receiving repeated calls from D&A Services, LLC and unsure whether it crosses the line into phone harassment? Many consumers report frequent and persistent contact, even after requesting verification or asking for communication to stop.
Who Is D&A Services LLC?
D&A Services, LLC is a nationally licensed and bonded third-party debt collection agency headquartered in Des Plaines, Illinois, a suburb of Chicago. The company was formerly known as Dynia & Associates, LLC (also spelled Alfred S. Dynia Associates), and you may see either name on collection letters or caller ID. D&A Services has satellite offices in Houston, Texas, and St. Petersburg (Clearwater), Florida.
| Detail | Information |
|---|---|
| Legal Name | D&A Services, LLC |
| Also Known As | Dynia & Associates, LLC; D & A Services |
| Founded | 2009 (incorporated; operating roots since 2006) |
| Headquarters | 1400 E. Touhy Ave., Suite G2, Des Plaines, IL 60018 |
| Satellite Offices | Houston, TX; St. Petersburg/Clearwater, FL |
| BBB Status | Accredited, A+ Rating |
| Main Consumer Phone | 877-314-4308 |
| Collections/Client Line | 773-902-1130 |
| Sales Line | 312-854-2567 |
| Website | dnasllc.com |
| Business Type | Third-Party Debt Collection Agency |
| President | Anthony Crews |
| Executive Director | Michael Prowicz |
| Complaint Manager | Jeff Hasenmiller |
| CIO | Diana Kucharski |
| Industry Memberships | Receivables Management Association International (RMAI); ACA International |
| Licensed/Bonded | Yes, nationally licensed and bonded |
The company is regulated in Illinois by the Illinois Department of Financial and Professional Regulation (IDFPR), 100 W. Randolph, Chicago, IL 60601, phone 888-473-4858.
Is D&A Services LLC a Scam?
If D&A Services is calling you, the first question is not whether they are a real company. The question is whether they are collecting a debt you actually owe, and whether how they are contacting you complies with federal law.
Why Is D&A Services LLC Calling Me?
D&A Services is calling you because a creditor has placed or assigned a past-due account with them for collection. They are a third-party collection agency, meaning they work on behalf of the original creditor or a debt buyer who purchased the account.
The most common reasons D&A Services contacts consumers include:
- Unpaid credit card debt: D&A Services, LLC collects charged-off credit card and retail card debts from banks and issuers such as Synchrony Bank, Crown Asset Management, and Comenity Bank.
- Auto loan deficiencies: They handle remaining balances after vehicle repossession when the sale price does not cover the loan amount.
- Medical debt: The company collects unpaid hospital and healthcare bills on behalf of medical providers.
- Student loans: Private student loan accounts in default may be placed with D&A for collection.
- Utilities and telecom: Unpaid phone, cable, internet, and utility bills can also be assigned to them.
- Wrong-party calls: Some consumers report being contacted due to skip-tracing errors linking their number to someone else’s debt, especially when the calls continue after they clarify they are not the debtor.
In our practice, clients frequently tell us they were never given written notice before the calls started, or that D&A began calling within days of an account being placed with them without mailing the required validation notice. Under FDCPA, a debt collector must send you a written validation notice within five days of its first communication with you, containing the amount of the debt, the name of the creditor, and your right to dispute the debt within 30 days.

D&A Services LLC Consumer Complaints
The Better Business Bureau (BBB) has recorded 24 total complaints against D&A Services in the last three years, with 6 complaints closed in the last 12 months. Consumer reviews on the BBB profile describe a pattern of aggressive calling, workplace intrusion, and calls to wrong parties.
In our practice, the same themes surface consistently: calls to wrong numbers, calls that continue after a consumer has asked them to stop, calls to workplaces, and abrupt hang-ups when a consumer challenges the collector’s basis for calling. These are exactly the patterns that federal law was designed to address.
D&A Services LLC Phone Numbers and Call Patterns
Consumers and consumer law practitioners have documented a large number of phone numbers associated with D&A Services and its predecessor Dynia & Associates. D&A often calls from numbers other than its main line, which can make it difficult for consumers to identify the caller without a reverse lookup.
Primary Consumer Line (main): 877-314-4308 Client/Collections Line: 773-902-1130 Alternate consumer numbers reported: 888-335-6729, 847-603-4549, 224-545-5814, 773-295-1627, 630-449-4279, 847-915-6422, 224-588-5453, 312-470-6651, 773-649-1832, 224-545-5357, 847-603-4522, 224-545-5362, 847-693-4976, 773-347-1333, 312-470-6653, 773-451-9731, 888-514-0212, 847-905-9909, 773-427-1900, 773-877-3266
Call patterns reported by consumers:
- Multiple calls per day to the same consumer, including back-to-back calls
- Calls to workplace numbers never associated with any account
- Calls to family members or people with the same last name as the debtor
- Pre-recorded or robotic-sounding voicemail messages left without identifying the nature of the call
- Calls at inconvenient hours, including calls that wake up consumers who work night shifts
- Calls that resume immediately after a consumer has requested that contact stop
Under the FTC’s guidance implementing the FDCPA and under the FCC’s regulations implementing the TCPA, specific calling patterns constitute violations. The FDCPA’s Regulation F rule, which became effective November 30, 2021, provides that a debt collector who calls a consumer more than seven times within a seven-day period, or within seven days of a prior conversation, is presumed to have engaged in harassment under 15 U.S.C. § 1692d(5). The TCPA (47 U.S.C. § 227) prohibits the use of an automatic telephone dialing system or an artificial or prerecorded voice to call a consumer’s cell phone without prior express consent.
Federal Court Cases Involving D&A Services LLC
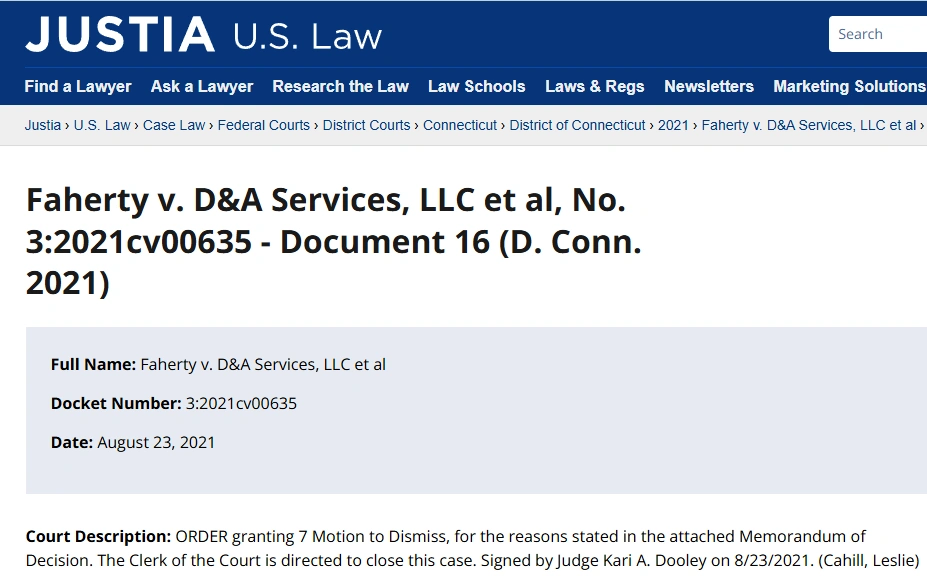
Case 1: Faherty v. D&A Services, LLC
Court: U.S. District Court, District of Connecticut Docket: No. 3:2021cv00635 Filed: May 4, 2021 Decided: August 23, 2021 Claims: FDCPA violations under 15 U.S.C. § 1692e (false, deceptive, or misleading representations) and § 1692g(b) (overshadowing of consumer’s right to dispute) Outcome: Dismissed on motion to dismiss; D&A prevailed
Kathleen Faherty brought a putative class action in the District of Connecticut alleging that a collection letter D&A sent her on November 9, 2020 was false and misleading under the FDCPA. The letter had been sent to collect a debt she owed Bank of America, N.A. that was placed with D&A after default. Faherty argued that the letter’s “Suspension Language” could be interpreted to mean that even a verbal dispute would trigger D&A’s obligation to cease collection, when in fact only a written dispute under § 1692g(b) would have that effect.
The court applied the “least sophisticated consumer” standard and found the letter was not deceptive. Judge Kari A. Dooley noted that the letter clearly and repeatedly required written notification to trigger suspension of collection efforts, and that Faherty’s interpretation was not one a reasonable, if unsophisticated, consumer would arrive at when reading the letter as a whole. The case was dismissed and the class action was closed.
In our practice, cases like Faherty illustrate that even when a court finds a particular collection letter not to be deceptive, the underlying disputes are real. Consumers receive collection letters that are confusing. The FDCPA’s “least sophisticated consumer” standard is designed to protect people who may not be fluent in legal or financial terminology. When a letter creates genuine uncertainty about what you must do to protect your rights, consulting with a consumer protection attorney before responding is the safest course.
Read more here: Faherty v. D&A Services, LLC
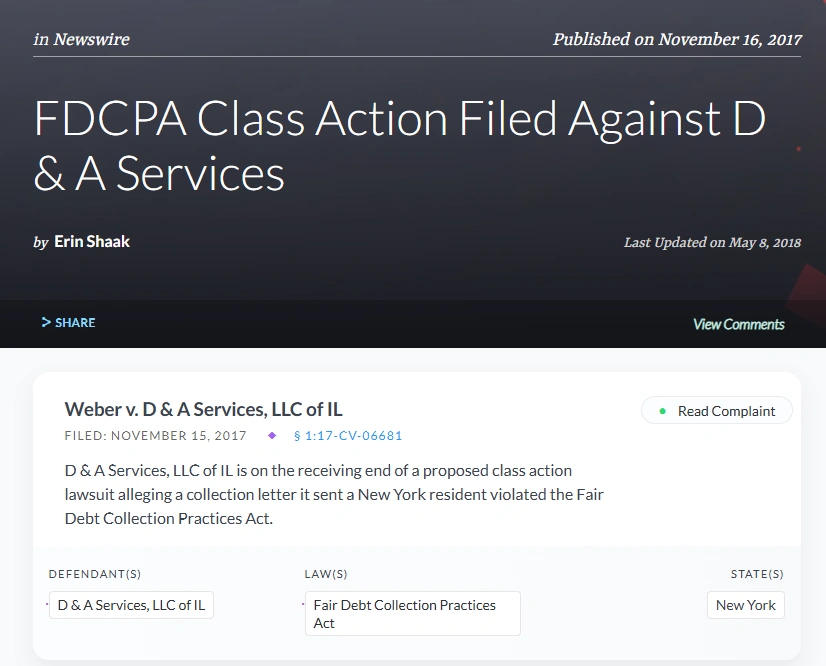
Case 2: Weber v. D&A Services, LLC of IL
Court: U.S. District Court, Southern District of New York Docket: No. 1:17-cv-06681 Filed: November 15, 2017 Claims: FDCPA violation under 15 U.S.C. § 1692e and § 1692f (false, deceptive, or misleading representations; unfair or unconscionable means)
A New York consumer filed a proposed FDCPA class action against D&A Services alleging that a collection notice the company sent listed only his “Current Balance” without disclosing whether that balance was subject to ongoing interest, late fees, or other charges that would cause it to increase over time. The suit argued that this made it impossible for the “unsophisticated consumer” to determine with certainty how much to pay to fully settle the account. If the balance was growing, the consumer needed to know so he could factor that into his payment decision. If it was not growing, the use of the phrase “Current Balance” implied urgency to pay quickly to avoid a higher balance, which would be misleading.
This case reflects a broader litigation pattern in which D&A faced multiple class actions in state and federal courts challenging the clarity of its collection notices regarding whether balances were accruing interest or other charges.
In our practice, one thing consumers often misunderstand is that they are entitled to clear, unambiguous information about their alleged debt before they pay a single dollar. A collection letter that obscures the total amount truly owed is itself a potential FDCPA violation, regardless of whether the underlying debt is valid.
Read more here: Weber v. D&A Services, LLC
FDCPA and TCPA Violation Reference Table
The following violations are the most commonly alleged against debt collectors like D&A Services LLC. If any of these match your experience, you may have a valid legal claim.
| Violation Type | FDCPA/TCPA Section | What It Looks Like With D&A Services |
|---|---|---|
| Excessive calls (harassment) | 15 U.S.C. § 1692d(5) | More than 7 calls in 7 days; calling 4 times per week while consumer is making payments |
| Calls to consumer’s workplace | 15 U.S.C. § 1692c(a)(3) | Calling work phone that was never associated with any account; interrupting meetings |
| Third-party disclosure | 15 U.S.C. § 1692c(b) | Contacting relatives or people with same last name to locate debtor; disclosing debt to non-consumer |
| False/misleading representations | 15 U.S.C. § 1692e | Collection letters with ambiguous “current balance” vs. “total amount due” language |
| Threatening arrest for civil debt | 15 U.S.C. § 1692e(4) | Telling consumer they can be imprisoned for failing to pay a credit card or loan balance |
| Failure to send validation notice | 15 U.S.C. § 1692g(a) | Starting collection calls without mailing a written notice within 5 days of first contact |
| Failure to cease after dispute | 15 U.S.C. § 1692g(b) | Continuing to call or collect after consumer sends written dispute or cease-and-desist |
| Calling wrong party repeatedly | 15 U.S.C. § 1692d | Repeatedly calling a number despite being told the debtor is not reachable there |
| Robocalls/auto-dialer to cell | 47 U.S.C. § 227 (TCPA) | Automated or pre-recorded calls to consumer’s cell phone without prior express written consent |
| Unauthorized bank debits | 15 U.S.C. § 1693 et seq. (EFTA) | Debiting consumer’s bank account without explicit written authorization for each transaction |
Your Legal Rights When D&A Services LLC Calls You
How to Stop D&A Services LLC From Calling You?
- Document every call. Write down the date, time, phone number, and what was said in each call. This record is your evidence. Save any voicemails.
- Do not admit the debt. Saying “I know I owe this” or making a partial payment can reset the statute of limitations in some states and affect your legal position. Ask for written verification first.
- Send a written debt validation request. Within 30 days of D&A’s first contact, send a written request demanding validation of the debt under 15 U.S.C. § 1692g. Send it via USPS certified mail, return receipt requested. Keep a copy. D&A must stop collection efforts until they provide verification.
- Send a written cease-and-desist letter. Under 15 U.S.C. § 1692c(c), you may demand in writing that D&A Services stop all communication. Send it certified mail. They may contact you one more time to acknowledge the request or inform you of specific legal action, but repeated calls after receipt of your letter are FDCPA violations.
- Check your credit report. Pull your reports from all three bureaus at AnnualCreditReport.com. If D&A has placed a collection account, you have the right to dispute it if the debt is invalid or if any information is inaccurate.
- File a complaint with the FTC. File at ReportFraud.ftc.gov. The FTC uses complaint data to pursue enforcement against debt collectors that engage in systemic violations.
- File a complaint with the Illinois IDFPR. If D&A is violating Illinois collection law, the IDFPR at idfpr.illinois.gov can investigate. Phone: 888-473-4858.
- File a complaint with your state Attorney General. Most state AG offices have a consumer protection division. Find yours at naag.org.
- Contact a consumer protection attorney immediately. If D&A Services has violated the FDCPA or TCPA, you may be entitled to statutory damages. Consumer Rights Law Firm PLLC handles these cases with no out-of-pocket cost. Call us at 877-700-5790 or visit our website.
About Us
Consumer Rights Law Firm PLLC is a law firm that specializes in helping clients who are facing harassment from debt collectors in any form, including telephone communication. Rather than suffer alone, contact our office to begin the process to stop their harassment. Our office has been assisting consumers since 2010. We have an A+ rating with the Better Business Bureau.
If you are interested in learning more about how to safeguard yourself and prevent harassment from D&A Services LLC. call us at 877-700-5790 for immediate assistance or visit our website.
Success Stories
- My elderly mother was getting bullied by a collector demanding payment for an old bill. They used scare tactics and threatened her credit. I contacted Consumer Rights Law Firm PLLC on her behalf, and they took care of it immediately. No more calls, and she was even awarded damages. They truly care about protecting people.
- I was getting nonstop robocalls from an agency claiming I owed a debt I didn’t recognize. They wouldn’t send anything in writing. Consumer Rights Law Firm PLLC not only got the calls to stop but also made sure my credit was protected. Their attorneys were responsive, empathetic, and highly skilled.
- Every time I picked up the phone, it was another debt collector harassing me. I started dreading phone calls altogether. Consumer Rights Law Firm PLLC stepped in, explained my rights, and sent formal legal letters that forced the collector to back off. They made sure I felt empowered again.
FAQs
Who is D&A Services LLC and why are they calling me?
D&A Services LLC is a third-party debt collector (formerly Dynia & Associates) based in Illinois. If they’re calling, they likely believe you owe a past-due debt, such as credit-card or personal-loan balances.
Is D&A Services LLC a legitimate debt collection agency or a scam?
They are a real, BBB-accredited debt collector operating for around 18 years. However, consumers have reported FDCPA violations, so it’s important to request verification.
Can D&A Services LLC legally harass me with calls?
No. Harassing calls, repeated ringing, threats, profanity, or calling at odd hours are prohibited under the FDCPA.
How should I respond if D&A Services LLC calls me?
Politely request written debt validation. Ask for debt details like amount, original creditor, and documentation. Under the FDCPA, they must send this within 30 days and pause collection until provided.
Can I tell D&A Services LLC to stop calling me?
Yes. You can send a written cease-and-desist request. Once received, they must stop calling except to inform you of legal actions or they’ve stopped collection entirely.
What if D&A Services LLC keeps calling after I ask them to stop?
Keep detailed records of calls, then file complaints with the CFPB or FTC. You may also have grounds to sue them for FDCPA violations.
Could D&A Services LLC affect my credit score?
They themselves don’t report, but they can pass a debt to an original creditor or buyer who may. Ensure the debt is valid and dispute if needed.
What are my legal rights if they violate debt-collection laws?
You can sue for FDCPA violations—including harassment or deceptive practices—and recover statutory damages (up to $1,000), plus legal fees.
What if I’m sued by D&A Services LLC?
Respond promptly to avoid a default judgment, dispute the debt in writing, and consider negotiating settlement or defending the lawsuit.
How can I definitively stop calls and resolve the issue?
Request verification, send a written cease-and-desist, then dispute inaccuracies. If needed, escalate to CFPB/FTC or consult a consumer attorney for possible settlement or lawsuit.
Phone Numbers May Be Associated With D&A Services
| 855-270-0852 | 224-387-5702 | 763-236-8110 |
| 855-977-2007 | 847-915-4061 | 312-470-6696 |
| 888-283-7649 | 224-545-5812 | 312-940-5581 |
| 847-693-4678 | 307-265-9091 | 224-545-5361 |
| 224-387-5703 | 773-295-4724 | 515-293-4725 |
| 224-545-5230 | 800-268-0514 | 877-314-4308 |
