

Credit Adjustments Inc. contact can be confusing when the account appears tied to a federal student loan, hospital bill, anesthesia charge, or older assigned balance. The first issue is not only the calls. The first issue is whether the company has current authority and whether the balance matches the original records.
In our practice, we often begin CAI files by comparing the collection letter against StudentAid.gov records, hospital ledgers, provider bills, and assignment documents. A recurring problem is that the consumer recognizes the original account but cannot confirm why this collector is involved. The next step is usually a written request for authority and itemization.
Why Is Credit Adjustments Calling Me About A Student Loan Or Hospital Bill?
The company may be contacting you because it previously handled defaulted federal student loan accounts or because a healthcare provider assigned an unpaid balance for collection.
Verified records connect the agency to U.S. Department of Education default collection work and healthcare receivables. Court records also connect the company to medical accounts involving hospitals and provider balances.
That matters because student loans and healthcare accounts often depend on outside records. A collector’s letter alone may not explain the current servicer, original provider, insurance adjustments, payment history, or assignment authority.
How Do I Know If The Collector Still Has Authority To Collect?
You can check the authority by comparing the collection notice with the current loan, hospital, provider, or creditor records.
For student loans, Federal Student Aid records matter because CAI appears among contractors that no longer manage student loans for ED. Public records also show the company later rebranded as Mammoth Tech, Inc., which makes the current authority and creditor identity especially important to verify.
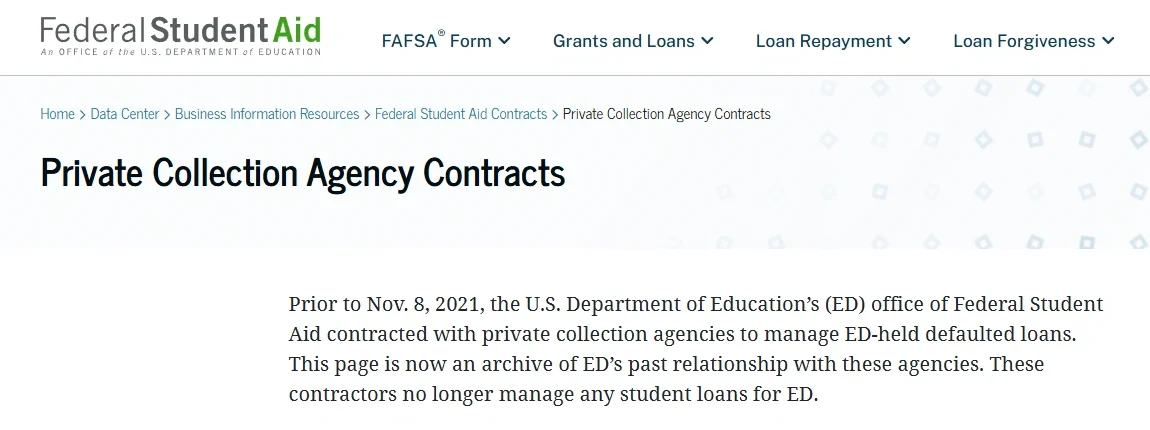
Source: U.S. Department of Education, Federal Student Aid
Clients who contact us often have a CAI letter but not the current federal loan record or hospital ledger. We usually look for a mismatch between the collector’s demand and the source account. If the authority is unclear, we usually start with a written dispute focused on who assigned the account and when.
Why Does The Balance Not Match My Records?
The balance may not match because the account includes provider adjustments, assignment changes, collection fees, payment charges, or incomplete account history.
Were Collection Fees Or Payment Charges Added?
Any added fee should be compared with the original agreement, collection letter, and payment disclosure. In Halvorsen v. Credit Adjustments, court filings alleged issues involving collection or delinquency fees and a credit-card payment charge. The case supports why itemization matters before payment.
Does The Hospital Or Provider Ledger Match The Collection Letter?
The hospital or provider ledger should match the collection amount before you assume the balance is accurate. Medical accounts can involve separate hospital, physician, anesthesia, or facility charges.
We regularly compare CAI medical balances against hospital statements, provider bills, insurance EOBs, and assignment records. One recurring issue is that the consumer recognizes the hospital but not the separate provider account. When that happens, we usually request the itemized medical ledger before discussing settlement.
Does My Federal Student Loan Record Show The Same Collector?
Your current federal student loan record should show who has authority now. If the collector’s letter does not match the current ED or servicer record, payment may not resolve the right account.
What Do Credit Adjustments Reviews And BBB Records Show?
The available BBB profile identifies the business as not BBB accredited and lists the rating as Not Rated.
The accessible BBB record did not provide detailed complaint narratives or a verified complaint timeframe that could support specific BBB complaint themes. That limits how strongly any Credit Adjustments reviews or Credit Adjustments complaints should be described.
Even with that limitation, the verified public record still points to the same practical issue: consumers should verify the account source, current authority, and balance support before paying or relying on the collector’s explanation alone.
Can The Company Keep Calling My Cell Phone?
The company’s ability to call may depend on how it obtained the number, what consent was given, and whether you later revoked permission.
Did The Company Get My Number From Medical Or Account Records?
In Baisden v. Credit Adjustments, the Sixth Circuit addressed medical-debt collection calls where phone numbers came through healthcare records. The court affirmed summary judgment for the company, but the case shows why admission forms and billing documents matter.
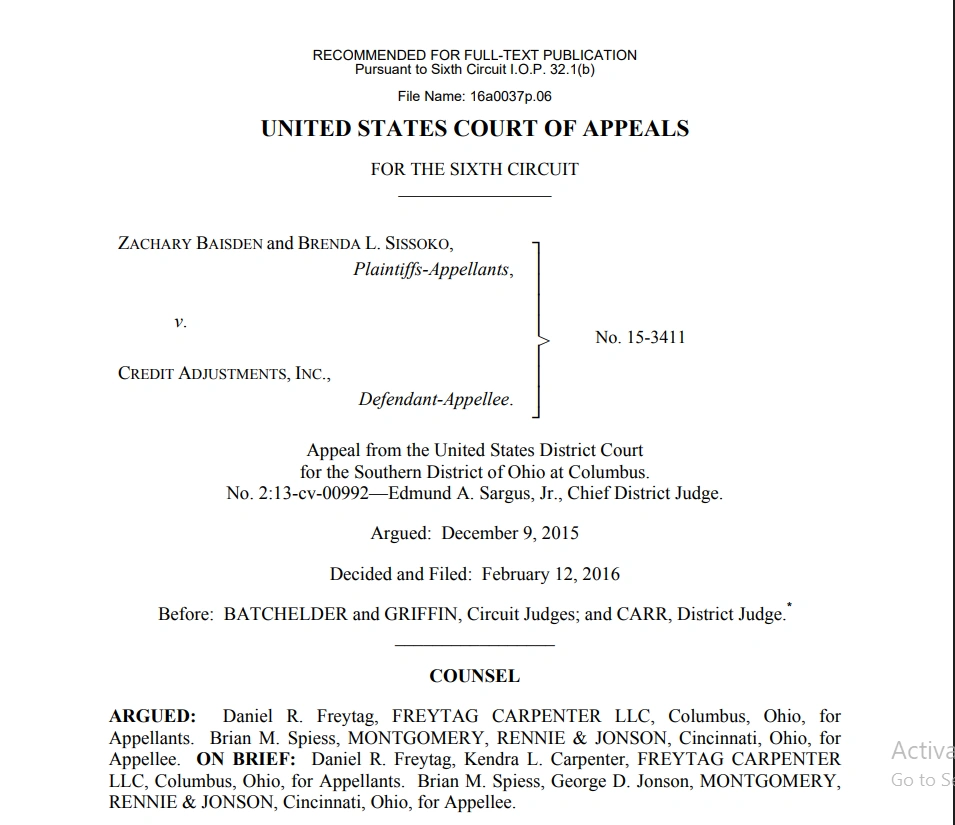
Source: U.S. Court of Appeals for the Sixth Circuit, Baisden v. Credit Adjustments, Inc., No. 15-3411.S
What If I Told The Collector To Stop Calling?
A stop-call request should be documented in writing. Keep call logs, voicemails, letters, and screenshots showing what was said and when.
Can Credit Adjustments Sue Me For Medical Debt?
Court records show the company has filed medical-debt litigation, so court papers should never be ignored.
In Credit Adjustments, Inc. v. Barlage, CAI sued over unpaid healthcare services, and the consumer raised counterclaims involving assignment issues. The dismissal of those counterclaims was affirmed, but the case still shows why consumers should check assignments, provider records, and bankruptcy history early.
One of the first records we examine in a CAI lawsuit file is the complaint amount next to the medical provider assignment and any bankruptcy discharge papers. A recurring issue is that the lawsuit amount may be accepted too quickly. The next step is usually checking whether the account was properly tied to the named provider.
What Should I Verify Before Paying The Collector?
Before paying, verify the account source, current authority, itemized balance, payment history, and any lawsuit or bankruptcy record.
| Record | What It Can Show |
| StudentAid.gov record | Current federal loan status and assigned servicer |
| Hospital or provider ledger | Original medical charges and adjustments |
| Insurance EOBs | Insurance payments, denials, or write-offs |
| Assignment records | Whether the collector has authority |
| Collection letter | Balance, account number, fees, and creditor name |
| Court records | Whether a lawsuit or judgment exists |
We frequently see consumers focus only on stopping calls while missing the larger account problem. With CAI files, we usually compare the demand against student loan records, medical ledgers, and court filings. If those records do not line up, the first move is usually a targeted dispute rather than a rushed payment.
How Can I Contact Credit Adjustments About My Account?
You can use verified public contact details, but keep copies of every communication.
| Item | Details |
| Company | Credit Adjustments, Inc. |
| Address | 1250 Geneva Blvd., Defiance, OH 43512 |
| Phone | (419) 782-3709 ext. 119 |
| Fax | (419) 784-9784 |
| Later name | Mammoth Tech, Inc. |
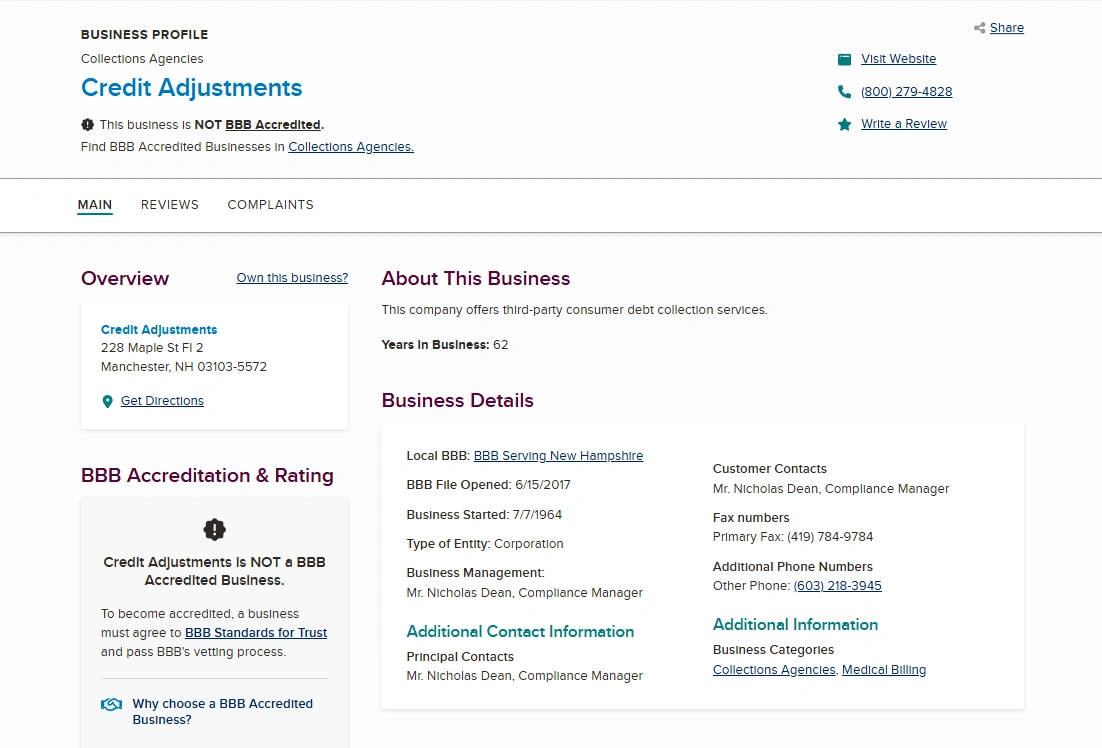
Source: BBB profile
How Can Consumer Rights Law Firm PLLC Review A CAI Account?
Consumer Rights Law Firm PLLC can review whether the contact, balance, and collection authority match the underlying student loan, medical, assignment, or court records.
In our practice, CAI matters often turn on records consumers do not have when the calls begin. We look at the creditor identity, current authority, itemization, call history, and any lawsuit papers. If the file shows a mismatch, we usually prepare the next response around the records, not the collector’s wording alone.
| Item | Details |
| Law Firm | Consumer Rights Law Firm PLLC |
| Address | 133 Main Street, Second Floor, North Andover, MA 01845 |
| Phone | +1 (877) 700-5790 |
| Fax | 844-636-9909 |
| help@consumerlawfirmcenter.com |
| Better Business Bureau | CRLF Better Business Bureau Profile |
Success Stories
I would highly recommend this law firm! They dealt with my claim very quickly and kept in communication. I wasn’t asked to pay any money for their services. Scott my representative was very professional and helpful!
Scott was amazing and very professional! He was very knowledgeable and took the time to explain everything and answer my questions. We were dealing with a very unprofessional debt collector. Im thankful I looked into our rights and what we could do and found Consumer Rights Law Firm. Dont ever let a debt collector try to bully you and tell you that you have no rights because you do!
Consumer Rights Law Firm is amazing! Scott was A+ all the way! He helped get a debt collector to stop harassing me and calling nonstop. I honestly thought it wasn’t real at first when they said there’d be no out-of-pocket costs but Scott proved me wrong! He was so easy to talk to and really cared about helping me.
He even got the debt completely removed and put a little extra change in my pocket. I was shocked. Thank you SO much, Scott! I’d 100% recommend Consumer Rights Law Firm PLLC to anyone dealing with the same kind of mess. Seriously, give them a call!
FAQs About Credit Adjustments Inc. Harassment
Why is the agency calling about my federal student loan?
It may relate to older defaulted student loan collection work, but you should verify current authority through Federal Student Aid before paying.
Does CAI still manage federal student loans for ED?
Federal Student Aid identifies the company among contractors that no longer manage student loans for ED, so current assignment should be checked.
Why does the Mammoth Tech name matter?
Public records show CAI later rebranded as Mammoth Tech, Inc., so consumers should verify the name, authority, and account source before paying.
Why is the collector calling about a hospital bill?
A hospital or medical provider may have assigned an unpaid balance, but the provider ledger should match the collection letter.
Can a medical bill include separate provider charges?
Yes. Hospital, anesthesia, physician, and facility charges may appear separately, so each balance should be matched to the correct provider.
What did Baisden v. Credit Adjustments involve?
It involved Telephone Consumer Protection Act (TCPA) claims over medical-debt collection calls and showed why healthcare forms and phone consent records matter.
What did Credit Adjustments, Inc. v. Barlage involve?
It involved a medical-debt lawsuit and assignment-related disputes, which shows why court papers and provider assignments matter.
Can CAI add payment or collection fees?
Any added fee should be checked against the original agreement, itemized ledger, and payment disclosure before payment.
What should I check before paying a student loan balance?
Check StudentAid.gov, the current servicer record, any default notice, and the collector’s written authority.
What if the company keeps calling after I object?
Keep call logs, voicemails, letters, and written stop-call requests so the call history can be reviewed against the account records.


